Readers comparing The Psychology of Money by Morgan Housel with I Will Teach You to Be Rich by Ramit Sethi are choosing between two different ways to improve their finances: understand the behavior behind money decisions, or follow a hands-on plan for changing those decisions. Housel focuses on how patience, risk, luck and personal history shape financial choices. Sethi focuses on practical systems for spending, saving, banking, debt and investing.

Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included

The Psychology of Money: Timeless Lessons on Wealth, Greed, and Happiness
- ✔ Author: Not specified in the supplied product details
- ✔ ASIN: 0857197681
- ✔ Stated subject: How people think about money and wealth

Personal Finance For Dummies
- ✔ Author: Not specified in the supplied product details
- ✔ ASIN: 1394207549
- ✔ Stated category: Personal finance
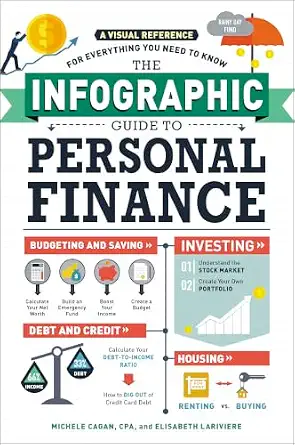
The Infographic Guide to Personal Finance: A Visual Reference for Everything You Need to Know
- ✔ Author: Not specified in the supplied product details
- ✔ ASIN: 1507204663
- ✔ Series: Infographic Guide Series
The distinction matters because knowing why people make money mistakes does not automatically tell you how to set up your accounts or automate savings. On the other hand, a system can be harder to follow if it does not fit your values or habits. Choose Housel if you want a concise, reflective guide to making steadier decisions; choose Sethi if you want concrete steps and are ready to put them into practice.
At a Glance
| Criteria | The Psychology of Money by Morgan Housel | I Will Teach You to Be Rich by Ramit Sethi | Winner |
|---|---|---|---|
| Primary focus | Money behavior, risk and long-term judgment | A personal finance system and conscious spending | Depends |
| Practical action steps | Principles and examples; limited setup instructions | Detailed steps for organizing accounts, saving and investing | B |
| Investing guidance | Broad lessons about patience and staying invested | Practical framework, with recommendations that readers should check against current circumstances | Depends |
| Budgeting and spending | Encourages personal priorities without a detailed budget system | Strong focus on spending plans and automation | B |
| Reading experience | Short, modular essays | Longer, conversational and directive | A |
| Best fit for beginners | Accessible for reflection, less complete as a how-to manual | Strong for readers who want a guided starting plan | B |
| Durability over time | High; centered on enduring behavioral ideas | Useful systems, though product details and recommendations can age | A |
The Psychology of Money: Timeless Lessons on Wealth, Greed, and Happiness
The Psychology of Money takes the top spot because its stated focus is both specific and central to personal finance: how people think about money and relate it to wealth, greed, and happiness. Financial choices are shaped by more than information, and a book organized around those human factors can help readers reflect on the assumptions behind their decisions. Compared with Personal Finance For Dummies, this title has a clearer stated point of view; compared with The Infographic Guide, it promises a thematic exploration rather than a visual reference format.That focus also defines the tradeoff. Readers who need a broad reference for financial tasks may prefer a general guide, while someone who learns best through diagrams may gravitate toward the Infographic Guide. The description does not specify chapters, exercises, or practical tools, so we should not assume this is a detailed how-to manual. It is the most compelling first read for readers whose goal is to think more deliberately about money, but those seeking topic-by-topic instructions should check the edition’s contents before choosing it as their only resource.
Pros:
- Clearly defined focus on how people think about money and wealth.
- Connects financial decisions with greed and happiness, bringing values into the discussion.
- Offers a distinct perspective alongside the lineup’s general-book and visual-reference options.
- Its stated themes can suit readers seeking reflection rather than a format-led overview.
Cons:
- The supplied description does not confirm practical exercises or step-by-step guidance.
- Specific coverage of budgeting, debt, investing, or other personal finance topics is not provided.
- Readers seeking a visual reference may find the Infographic Guide’s stated format a closer fit.
Best for: Readers who want to reflect on the beliefs and emotions that shape their financial decisions.
Not ideal for: Readers who primarily need a structured reference, detailed task-by-task instruction, or an explicitly visual presentation.
Bottom line: We rank it first for its clearly stated focus on money behavior, while advising readers who need practical reference coverage to verify the contents or pair it with a general guide.
“We rank it first for its clearly stated focus on money behavior, while advising readers who need practical reference coverage to verify the contents or pair it with a general guide.”
Personal Finance For Dummies
Personal Finance For Dummies is the lineup’s broadest candidate by title: it presents itself as a personal finance book without narrowing its promise to psychology or visual explanation. That makes it a plausible choice for a reader who wants a general entry point and has not yet decided which money topic deserves attention. In contrast, The Psychology of Money signals a focused discussion of behavior, and The Infographic Guide signals a particular way of presenting information. This title’s apparent breadth is its main distinction.We need to keep that recommendation qualified: no further product description or topic list was supplied. We cannot confirm whether the book covers budgeting, credit, saving, investing, taxes, or planning, nor how current or detailed its guidance is. Its familiar series name may make it seem approachable, but that alone does not establish reading level or instructional quality. Readers should inspect the edition and contents if they need help with a particular decision. For a broad orientation, it is the sensible second pick; for a known interest in money psychology or a strong preference for visual learning, the other two have clearer stated matches.
Pros:
- Its title makes a broad personal finance focus clear.
- Could serve readers still deciding which area of personal finance to explore.
- Provides a contrast to the psychology-focused and visual-reference choices in this roundup.
- The straightforward title makes its general category easy to identify.
Cons:
- No detailed description was provided to confirm topics, structure, or level of instruction.
- The supplied details do not identify a distinctive method or format.
- Readers should verify the edition and contents before relying on it for a specific financial task.
Best for: Readers who want to investigate a general personal finance introduction before choosing a narrower topic.
Not ideal for: Readers who need confirmed coverage of a specific financial subject or want a book with a clearly stated thematic or visual approach.
Bottom line: We place it second as the likely broad introduction, with the important caveat that its actual topic coverage is not established by the available details.
“We place it second as the likely broad introduction, with the important caveat that its actual topic coverage is not established by the available details.”
The Infographic Guide to Personal Finance: A Visual Reference for Everything You Need to Know
The Infographic Guide to Personal Finance earns a distinct place through its visual-reference format. For readers who prefer information arranged visually, that presentation may make broad topics easier to scan and revisit than a discussion centered on money psychology. It is also the only title here explicitly identified as part of a series: the Infographic Guide Series. Compared with Personal Finance For Dummies, its differentiator is clear even though the supplied details about that other book are sparse.The same format may not satisfy readers who want extended explanation or a guided sequence of decisions; the description does not say how much text accompanies its visuals or which subjects receive detail. The phrase “everything you need to know” is part of the title, but the available information does not establish comprehensive coverage. We therefore rank it third overall, while making it the strongest match for visual learners and readers who want a visual reference. Readers seeking a reflective treatment of financial behavior should start with The Psychology of Money, and those needing a specific task covered should verify the guide’s contents before relying on it.
Pros:
- Explicitly presents personal finance information in a visual reference format.
- Its format gives it the clearest role distinction in this comparison.
- Belongs to the Infographic Guide Series.
- May suit readers who prefer scanning and revisiting visual material.
Cons:
- The supplied details do not specify which financial subjects are covered.
- The extent of accompanying explanations and practical instruction is not provided.
- Readers who want a focused discussion of money behavior may prefer The Psychology of Money.
Best for: Visual learners who want a personal finance reference presented in infographic form.
Not ideal for: Readers who prefer extended prose, need confirmed step-by-step instruction, or want a specific topic’s depth established before buying.
Bottom line: We recommend it to visual learners who value the stated infographic format, while ranking it below the more clearly specified subject focus of The Psychology of Money.
“We recommend it to visual learners who value the stated infographic format, while ranking it below the more clearly specified subject focus of The Psychology of Money.”
As an Amazon Associate we earn from qualifying purchases.
Key Differences
The books differ most in what they expect the reader to do next. Housel asks readers to examine the stories, emotions and assumptions that influence their choices. His lessons can help someone resist panic, avoid overconfidence and stay patient. They are not a substitute for a budget, debt payoff schedule or account setup guide. Sethi gives readers a more direct route from reading to action: organize money, decide what spending matters, automate recurring decisions and invest according to a plan.
That makes I Will Teach You to Be Rich the stronger single purchase for someone who wants to change day-to-day money management. Housel is the better match for readers who already know the basics but want to make more durable decisions, especially under uncertainty. The books also age differently: principles about behavior tend to last, while specific account or product suggestions can change. Readers should treat Sethi’s operational guidance as a framework and verify current fees, tax rules and investment options before acting.
Detailed Comparison
Primary focus (major difference)
Housel explores how people think and feel about money, using stories to show how risk, luck, time and personal experience affect decisions. Sethi concentrates on building a workable financial routine, from spending choices to saving and investing. Neither focus replaces the other, so the winner depends on the reader’s immediate need. If the main problem is inconsistent behavior or fear of market swings, Housel has the edge. If the problem is not knowing how to organize finances, Sethi wins. The difference is major because each book answers a different question.
Practical action steps (I Will Teach You to Be Rich by Ramit Sethi wins — major)
Sethi is the clear winner for implementation. His approach lays out actions readers can use to structure accounts, automate transfers and make a plan for spending and investing. Housel offers memorable principles, but readers must translate them into a personal system themselves. That is a major difference for a person who wants to finish a chapter and take a specific next step. Readers who already have routines may find Housel’s less prescriptive approach more useful, but beginners seeking a checklist will get more direct help from Sethi.
Investing guidance (moderate difference)
Housel wins on the behavioral side of investing: he emphasizes patience, the power of time and the value of avoiding decisions that can permanently damage a plan. Sethi offers a more actionable framework for incorporating investing into an overall system. Neither book should be treated as individualized financial advice, and recommendations tied to particular products or account rules need a current check. For a reader who already invests but is tempted to react to every market move, Housel has the stronger lesson. For someone who needs investing to become part of a routine, Sethi is more useful. This is a moderate, goal-dependent gap.
Budgeting and spending (I Will Teach You to Be Rich by Ramit Sethi wins — major)
Sethi wins because conscious spending and automation are central to his framework. He encourages readers to set priorities and build a system around them, rather than treating every expense as equally deserving of a cut. Housel supports the broader idea that money should serve personal goals, but he does not provide a comparable budgeting method. The difference is major for readers who struggle to control spending or want a repeatable monthly process. Someone who already has a working budget may prefer Housel’s wider perspective on why financial freedom matters.
Reading experience (The Psychology of Money by Morgan Housel wins — minor)
Housel’s short, self-contained essays make it easier to read in brief sessions and return to a specific idea. Sethi’s conversational, directive style takes readers through a more connected process, but the book is longer and makes more requests of the reader. Housel wins by a minor margin for people who want a quick, reflective read; Sethi is a better experience for those who prefer an extended guide with a clear sequence. The practical consequence is simple: choose the format you are likelier to finish and use.
Beginner usefulness (I Will Teach You to Be Rich by Ramit Sethi wins — major)
Sethi is more useful for a beginner who wants to set up a system and is ready to act. Housel is readable without specialist knowledge, but it teaches judgment more than financial mechanics. That distinction is major for someone who has never built savings, chosen an investment account or organized recurring bills. A beginner who is emotionally overwhelmed by money might still start with Housel, but should pair it with reliable, current instructions for the specific tasks they need to complete.
Durability over time (The Psychology of Money by Morgan Housel wins — moderate)
Housel has a moderate edge because its central lessons concern behavior and uncertainty, subjects that change slowly. Sethi’s systems are still useful as frameworks, but particular providers, fees, tax rules and account features can become outdated. Readers can preserve the value of both books by separating durable principles from time-sensitive specifics. If you want a book to revisit over many years, Housel is the safer choice; if you want a system to implement now, Sethi is more immediately actionable.
The Psychology of Money by Morgan Housel: Pros and Cons
Pros:
- Clear lessons about risk, patience and long-term behavior
- Short essays are easy to read in small sessions
- Ideas remain useful as financial products and rules change
Cons:
- Offers few step-by-step instructions for budgeting or account setup
- Readers must turn broad principles into their own routines
- May feel too abstract for someone facing an immediate money-management problem
I Will Teach You to Be Rich by Ramit Sethi: Pros and Cons
Pros:
- Gives readers a practical framework for spending, saving and investing
- Emphasizes automation and repeatable financial routines
- Direct style can help beginners move from intention to action
Cons:
- Longer and more prescriptive than Housel’s book
- Some operational details may need updating
- The system requires follow-through and adaptation to individual circumstances
Who Should Choose What
Choose The Psychology of Money by Morgan Housel if:
- You have basic money routines and want to make calmer decisions about risk and uncertainty.
- You prefer concise essays and ideas that remain relevant over time.
- Your main challenge is impulsive or fear-driven financial behavior rather than a lack of instructions.
Choose I Will Teach You to Be Rich by Ramit Sethi if:
- You want a practical plan for organizing spending, saving and investing.
- You are new to managing money and need actions you can adapt into a routine.
- You value a directive guide and are willing to check current rules and products before acting.
Skip both if: You need advice tailored to complex taxes, legal obligations, business finances or a personal debt crisis; consult a qualified professional or a reputable nonprofit counselor for guidance suited to your circumstances.
Value for Money
Both books are typically available in inexpensive print or digital editions, so the bigger question is whether the content solves your current problem. If you will use Sethi’s system to organize accounts, automate savings and establish an investing routine, paying a little more for his longer guide can be worthwhile: its value comes from implementation. If you mainly want perspective and a book you can revisit, Housel offers strong long-term value in a shorter read.
For most first-time personal finance readers seeking a single book, Sethi is the better value because it covers more of the practical setup work. Pay for Housel when your basics are already in place and better judgment is the missing piece. Neither purchase replaces up-to-date checking of financial products, fees or rules.
Final Verdict
Choose I Will Teach You to Be Rich if you want a usable system for managing money and will act on its guidance. It is the stronger all-around starting point for readers who need help turning good intentions into routines. Choose The Psychology of Money if you already know the mechanics and want to improve the way you respond to risk, time and uncertainty.
The biggest deciding factor is whether you need instructions or perspective. If you are unsure, start with Sethi for practical structure, then read Housel to strengthen the habits and judgment that help you stick with it.
Frequently Asked Questions
Which book is better for someone with no personal finance experience?
I Will Teach You to Be Rich is usually the better first choice because it provides a more practical route into spending, saving and investing. New readers should still check that any product or account details apply where they live and today.
Does The Psychology of Money teach budgeting?
It offers perspective on how money relates to behavior and personal priorities, but it is not a detailed budgeting manual. Readers looking for a spending plan and routine will find more direct guidance in Sethi’s book.
Which book is more useful for investing?
Housel is especially useful for the emotional side of investing, including patience and risk. Sethi is more useful for making investing part of a broader financial system. The better choice depends on whether you need behavioral perspective or practical structure.
Should I read both books?
Yes, if you want both a financial routine and a better understanding of the behavior that can derail it. Start with Sethi if you need to organize your money, or Housel if you already have a system and want to strengthen your decision-making.
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.